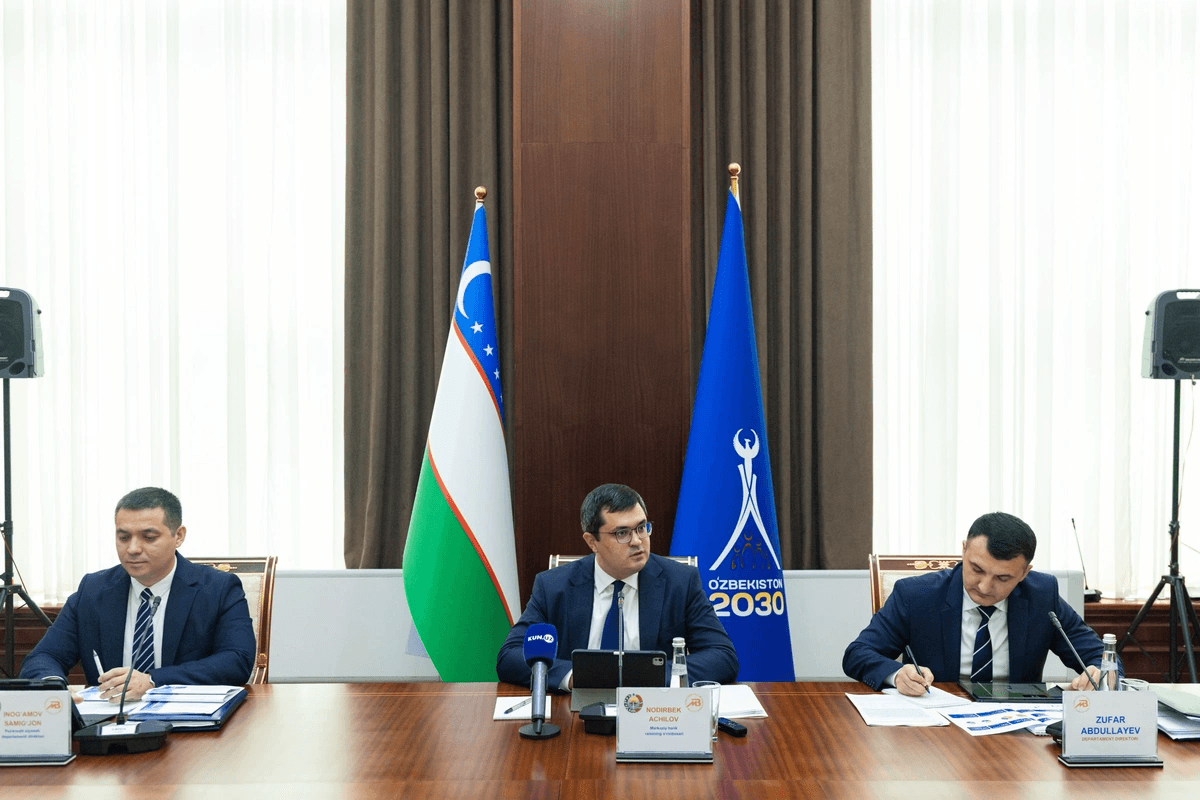
Speaking at a press conference on November 3, Ochilov said the possibility of cutting the rate below 10% was outlined in the Central Bank’s monetary policy guidelines for 2027–2029. The key rate currently stands at 14%.
He stressed, however, that any reduction would depend on inflation developments rather than follow a predetermined schedule.
“Over the past period, we have focused more on developing the domestic money market and strengthening the channels through which we influence the cost of short-term money. Over the next three years, an important task will be to increase our influence on the cost of medium-term funds,” Ochilov said.
The Central Bank also plans to improve its monetary policy operating framework, including reviewing the volume and range of instruments used in operations with maturities of up to one year.
Ochilov said the regulator would reassess the current interest rate corridor, which extends two percentage points around the key rate. If inflation returns to the target and inflation expectations continue to ease, the Central Bank could consider narrowing the corridor and gradually reducing the key rate to single digits during the 2027–2029 policy horizon.
Ochilov said the corridor could become relatively wide under such conditions, making it necessary to consider narrowing it alongside a gradual reduction in the key rate. He emphasized that this was a possible policy scenario, not a commitment to a specific rate trajectory.
Why is the key rate still at 14%?
Despite easing inflation expectations and relatively stable price growth in recent months, the Central Bank believes that strong domestic demand and external risks continue to exert upward pressure on prices.
Annual inflation stood at 6.4% in September. However, the regulator said recent price movements had been driven largely by supply-side factors, and it remained uncertain whether their effects would be temporary or more persistent.
The Central Bank is particularly concerned about the secondary effects of price increases – when higher costs for certain goods and services feed into broader inflation and influence public expectations about future prices.
“Our main focus is on the secondary effects of price changes. The decision to maintain tight monetary conditions is intended precisely to prevent these effects from spreading and inflation expectations from strengthening,” Ochilov said.